Too often, you hear the lender’s question only after the case has gone in.
Finsensa asks it first.
Know whether the case stands up before the lender sees it.
See the questions a lender’s credit team is likely to ask on a limited-company term loan, and answer them in the credit paper before you submit.
A complete file isn’t the same as a case that stands up.
Having every document is the start, not the finish. The things that slow a deal down are usually already sitting in the file.
You’re paid on completion. Finsensa helps you find these while the case is still on your desk, not after the lender has come back.
Apply for founding accessSpeed comes from fewer rounds, not faster typing.
Every question a lender sends back after submission is another trip through your client. Finsensa brings those questions forward, so they’re answered once, before the case goes in.
Illustrative. The lender still decides, and may still ask questions. The aim is that the ones you could have answered are already in the paper.
Finsensa does the reading, the numbers and the write-up. You do the judgement.
One case, start to finish
Example case. Synthetic data, not a real business.- Borrower
- Precision engineering, limited company
- Facility
- £150,000 term loan
- Term
- 60 months
- Purpose
- CNC machining centre and stock
- The question
- The use of funds says £36,000 of steel stock. The supplier’s quote is for titanium and alloy bar. An underwriter would ask which it is.
- The answer
- The credit paper flags it before submission, so you can correct the description or explain it before the lender ever sees it.
- Also in this case
- A £38,000 receipt nobody could evidence. The credit paper leaves it out of repayment capacity, discloses it, and shows the cover without it.
Five questions a credit team will ask on a limited-company term loan
Think of a case on your desk now. Mark each one: would you have the answer ready before you submit?
- Can the business afford it after tax and existing debt?Lenders look at the cash left after tax, drawings and every existing facility, not profit before tax. Have the existing borrowing schedule to hand.
- Do the bank statements tell the same story as the accounts?Large or unusual receipts will be queried. Know where anything that isn’t trading income came from, and have the evidence.
- What exactly is the money for?The use of funds, the quotes and the invoices should describe the same thing at the same price.
- What happens if the main customer goes?If one customer is a large share of income, expect questions on the contract, how long it has run and what else is coming in.
- What stands behind the loan?Security, guarantees and the directors’ own position. A purchase price is not a valuation.
What goes to the lender
Three documents, built from the case you’ve reviewed.
- Credit paperThe case, written the way a credit team reads it.
- Financial workbookEvery key figure, with the document it came from.
- Supporting documentsIndexed, so the credit team can find each one quickly.
Our promises
Your name is on the case. You stay in charge of it, and these are the lines we don’t cross.
- Nothing reaches a lender until you’ve approved that exact version.
- We never pick the lender, and we never contact your client.
- Every key figure shows the document it came from.
- Your judgement is recorded as yours, never presented as fact.
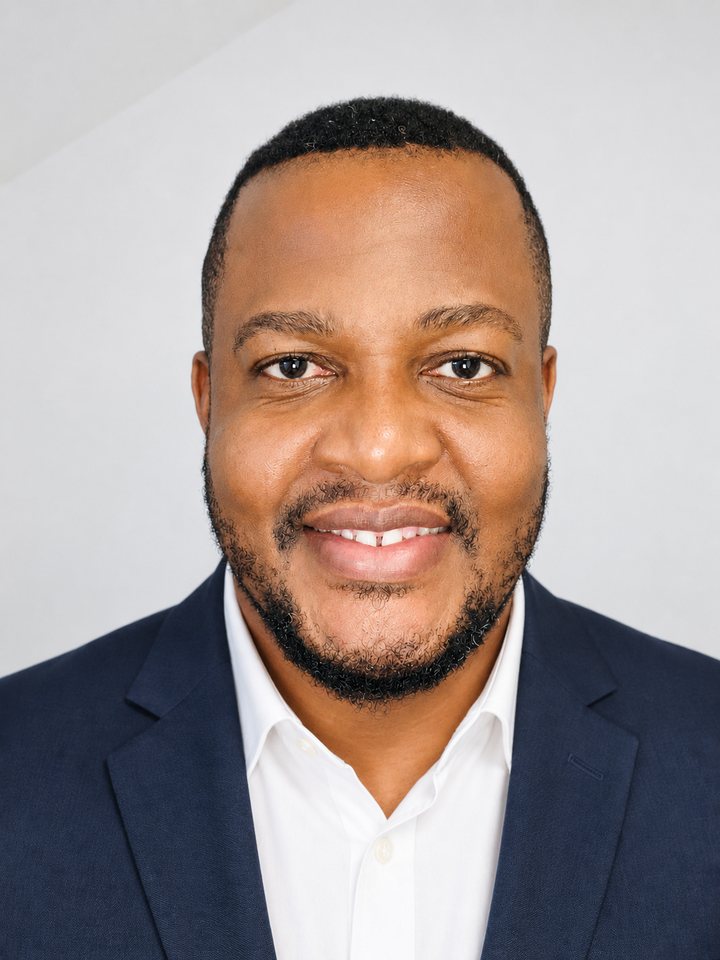
I spent over ten years in bank credit, including SME lending at Stanbic IBTC, part of Standard Bank Group, where I managed a business loan portfolio equivalent to over £100 million. I read credit papers like these from the lender’s side of the desk.
“This is the credit paper I wanted on my desk.”
Ikenna EgwimFounder, Finsensa
We take on a few broker firms at a time.
Each one is onboarded personally. Founding brokers get our best terms.
- Your first caseFree
- Every case after thatStandard price £199. No subscription.£149
Founding terms are for brokers who join before we open more widely.
What happens after you apply
- Ikenna replies by email.
- A 20-minute call, if you want one.
- You sign the terms, then start your first case.
Apply for founding access
Email us and Ikenna will reply personally. Tell us your role and roughly how many business lending cases you prepare a year.
Apply by emailBook a 20-minute walkthroughNo sales calls unless you ask for one.
We use these details only for your application. Privacy notice.
Questions brokers ask
What does Finsensa actually do?
It shows you what a lender’s credit team is likely to ask before the case goes in. Then it produces the credit paper, financial workbook and supporting documents from the case you’ve reviewed, so you don’t write it up twice.
I already use ChatGPT or other AI tools on my deals. Why would I use this?
General AI tools give you a draft you still have to check line by line. Finsensa gives you a credit paper, a financial workbook and indexed supporting documents in the form a credit team reads, with every key figure tied to the document it came from. Nothing leaves until you approve it.
How is AI used?
Machine learning reads the documents and sorts transactions, using a document-reading service and a small model that runs on our own servers. Figures and calculations follow fixed rules. No generative AI is used anywhere in Finsensa.
How much of my time does it take?
Finsensa does the reading, the figures and the first draft. Your time goes on answering the questions it raises and approving the result.
What does it cost?
Founding brokers’ first case is free. After that, founding brokers pay £149 per case, against a standard price of £199. There’s no subscription.
What do I need to bring?
The evidence you already collect for the case: accounts, bank statements, VAT returns and any supporting documents.
Does Finsensa make lending decisions or contact my client?
No. Finsensa doesn’t lend, choose or recommend lenders, contact your client or give credit advice. You decide where the case goes, and you send it.
Will the lender see my firm’s name?
Not on the credit paper yet. For now, it shows your name as the person who prepared it, alongside Finsensa’s. Adding your firm’s name is next on our list.
Is Finsensa FCA-regulated?
No. Finsensa Ltd is not authorised or regulated by the Financial Conduct Authority. Finsensa is software that brokers use to prepare their own cases. It doesn’t lend, introduce borrowers to lenders, recommend lenders, contact your client or give credit advice. You decide where a case goes, and you submit it.
How is my client’s data handled?
You stay in control of it. You’re responsible for your client’s information as the data controller. Finsensa only processes it to prepare your case, on your instructions, under a data processing agreement you accept before anything is uploaded. Apart from the providers that run Finsensa, nothing is shared unless you send it or the law requires it. Your client’s data is held in the UK and the EU, and is never used to train AI models. Inactive cases are deleted 12 months after the last activity, and you can ask for deletion sooner. If something goes wrong with your client’s data, we’ll tell you within 48 hours. Finsensa is registered with the ICO (ZC137201). Our data processing agreement is on our website, the list of providers we use is available on request, and the full detail is in the privacy notice.
What if something goes wrong?
Email hello@finsensa.com with “Complaint” in the subject line. Ikenna, the founder, reads every one and replies personally.
Key facts
| Scope | |
|---|---|
| Covered now | Term loans for UK limited companies. |
| Not covered | Sole traders, partnerships, and asset, invoice and property finance. |
| Your client’s data | |
| Who’s in control | You’re the controller. Finsensa processes your client’s data only on your instructions. |
| Data processing agreement | Accepted before anything is uploaded. It’s on our website, and our provider list is available on request. |
| Data protection registration | Information Commissioner’s Office, number ZC137201. |
| Where it’s held | The UK and the EU. |
| AI training | Never used to train AI models. |
| How long case data is kept | Inactive cases are deleted 12 months after the last activity. Earlier deletion on request. |
| Breach notification | We tell you within 48 hours of becoming aware of a breach affecting your client’s data. |